Key takeaways
- September 17, 2026: initial closing of an anticipated $3.9B Series F.
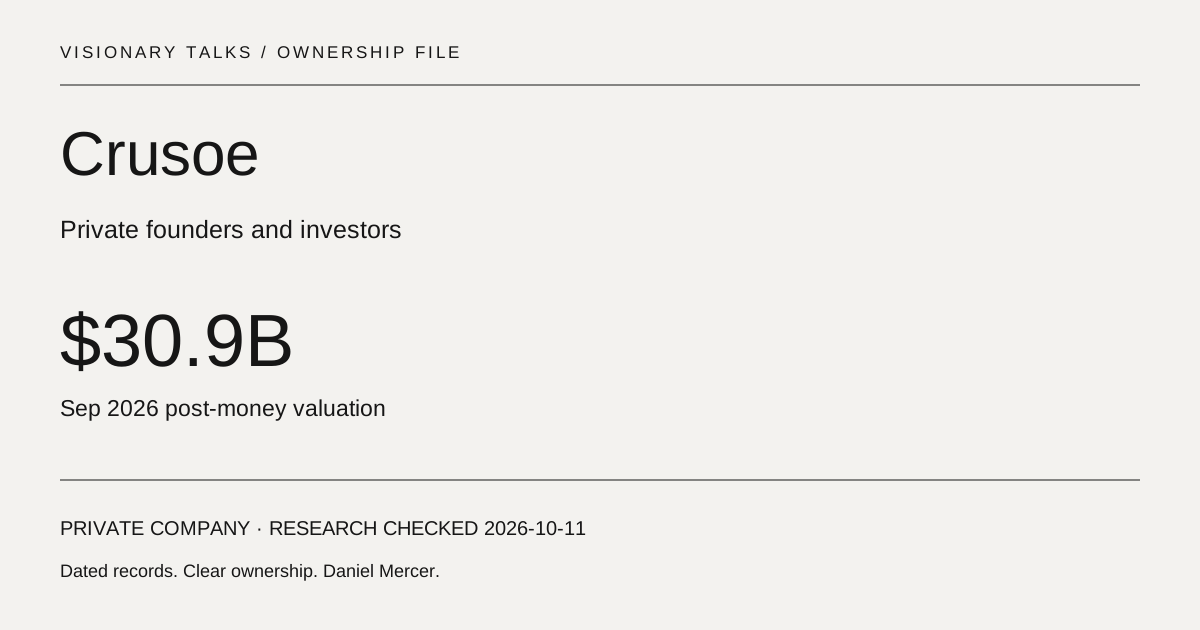
- The company disclosed $30.9B post-money and three co-leads.
- October 2025: Series E likewise described an initial closing and a valuation above $10B.
- A large contracted-value figure is not annual revenue, cash collected or corporate equity value.
What changed in 2026
The Series F release is more qualified than its headline. It reports an initial closing of an anticipated financing. I do not rewrite that as proof that all $3.9B had closed on the announcement date.
The source also publishes business activity metrics. They help describe demand, but do not disclose the full shareholder allocation. A total contracted value spans contractual periods and performance obligations; it cannot simply replace revenue or a share-price denominator.
Who owns Crusoe?
The investor syndicate includes financial funds and strategic capital. The co-leads have defined participation roles in this round, without published current percentages or voting power. A sovereign-linked investor is one owner in a syndicate, not evidence that the entire company is state-owned.
The Series D record names earlier holders, while the Series E announcement adds another dated participation map. A fund absent from a later short list has not necessarily exited. A complete current register would need holdings and transfers, not just names from successive press releases.
| Holder | Type | Stake / basis | Voting rights | Source / date |
|---|---|---|---|---|
| Founders | Founding team; allocations unavailable | Not disclosed | Not disclosed | www.crusoe.ai 2018 history |
| Atreides Management | Series F co-lead | Not disclosed | Not disclosed | www.crusoe.ai 2026-09-17 |
| Mubadala Capital; Valor Equity Partners | Series E and F co-leads | Not disclosed | Not disclosed | www.crusoe.ai 2026-09-17 |
| Founders Fund | Series D lead; later named participant | Not disclosed | Not disclosed | www.crusoe.ai 2024-12-12 |
| GIC; Nvidia; QIA; TPG; Radical Ventures | Named Series F participants | Not disclosed | Not disclosed | www.crusoe.ai 2026-09-17 |
Who owns Crusoe’s infrastructure versus Crusoe’s shares?
Corporate equity, a project interest and a contract for compute are different assets. A data-center venture can have its own owners, financing and customer obligations. A headline project budget does not therefore establish a valuation for all shares of the operating company.
The same applies to hardware and contracted capacity. Ownership of servers, leases of space, rights to power and customer commitments can be held under different agreements. An investigation should identify which entity owns each right before consolidating them into one claim.
That is why the product connection to Cursor’s ownership story is commercial context. Crusoe’s Series E release names Cursor among users of its platform. A compute customer is not automatically a corporate parent or equity holder.
The data-center company and the assets beneath it
An investor’s interest in Crusoe is a company-level ownership claim. The owner of a specific data center, a project vehicle, a financing security and a long-term customer contract may be different entities. A complete asset map would require project documents, rather than treating the corporate investor list as the ownership list for every facility.
The 2025 financing release describes a company increasingly focused on AI infrastructure and notes the sale of its Bitcoin mining business to NYDIG. That is material when reading an early-to-late valuation chart: the original mix of activities and the continuing business are not automatically the same perimeter. It is also why a past energy-and-crypto description may mislead readers about the present company.
My comparison of the $2.8B Series D and $30.9B Series F benchmarks yields roughly 11 times. The wide ratio calls for a labelled logarithmic chart. It does not supply a value for the intervening Series E, whose announcement describes an expected valuation above $10B. The table preserves that lower bound; the graph does not replace it with exactly $10B.
The $140B-plus total contract value reported alongside Series F is a different measure again. It describes aggregate commitments across their terms, rather than annual recognized revenue. Dividing a valuation by that figure would not produce a normal annual-sales multiple. I would need contract durations, execution conditions and revenue recognition to make the economics comparable.
The initial closing also deserves careful wording. The company announced an initial close of an anticipated $3.9B round. That establishes an announced financing event and its stated benchmark, while leaving the final aggregate capital subject to completion. For an IPO thesis, I would watch execution and financing alongside the public filing process; the label pre-IPO does not itself guarantee an exit date.
The share issuer and Cloud contract are different entities
The Cloud legal center identifies Crusoe Technologies LLC and affiliates in its service terms. The SEC securities filing instead identifies Crusoe Inc. A customer’s contracting entity and the issuer in a financing document answer different questions. I do not treat a Cloud service agreement as evidence that customers own the group or that a disclosed investor owns each operating asset directly.
How the founders built Crusoe
The company’s origin account connects Chase Lochmiller and Cully Cavness to its 2018 founding. The original energy-and-compute problem is useful context for the later AI infrastructure business.
That evolution does not mean each historical activity remains inside today’s corporate perimeter. The company’s later announcements describe a focus on AI infrastructure. For a full valuation comparison I would reconcile divested operations, project structures and continuing assets before treating early and late values as economically identical.
Funding and valuation history
A fully closed amount, initial closing and anticipated final size should not carry the same label. The table retains the distinction so readers can see what the company actually claimed at each date.
The Series E valuation is not an exact $10B point. I keep the company’s expected lower-bound wording and omit it from the numerical plot. The two exact valuation observations span more than ten times, so their chart uses a visibly labeled logarithmic scale.
The $3.9B headline divided by $30.9B is about 12.6%, but the numerator is an anticipated round size. It is not an established percentage of shares already issued at the initial closing, nor the combined stake of the three leads. I would need closing amounts and share terms for either conclusion.
| Date / event | Amount | Valuation | Lead / counterparty | Evidence |
|---|---|---|---|---|
| 2024-12-12 Series D | $600M closed | $2.8B | Founders Fund | www.crusoe.ai disclosed |
| 2025-10-24 Series E initial closing | Anticipated $1.375B | Expected above $10B | Mubadala Capital; Valor | www.crusoe.ai disclosed |
| 2026-09-17 Series F initial closing | Anticipated $3.9B | $30.9B post-money | Atreides; Mubadala; Valor | www.crusoe.ai disclosed |
| 2026-09-17 Form D: options, warrants or other rights | $595,943,098 sold; 52 investors | Not disclosed | Allocations not disclosed | SEC disclosed |
Crusoe: dated funding valuations
USD billions · priced rounds only
Scroll horizontally to see every column. Keyboard: focus the chart and use the arrow keys.
Logarithmic scale. Baseline 0.1 in the displayed units; equal vertical distances represent equal ratios. Missing values are not interpolated.
Separate round observations. Tenders, debt, proposed deals and valuation lower bounds are excluded. No values between rounds are estimated.
I plot the two exact financing valuations in this ledger on a logarithmic scale because the later value is about 11 times the earlier one. The middle lower-bound observation stays in the table. Bars represent individual events, with no interpolation.
Crusoe ownership timeline
| Date | Event | Ownership after event | Money / basis | Source |
|---|---|---|---|---|
| 2018 | Company founded | Private founders and early backers | No founding allocation disclosed | www.crusoe.ai |
| 2024-12-12 | Series D closes | Private shareholders including Founders Fund syndicate | $600M; $2.8B | www.crusoe.ai |
| 2025-10-24 | Series E initial closing | Private syndicate led by Mubadala and Valor | Anticipated $1.375B; expected > $10B | www.crusoe.ai |
| 2026-09-17 | Series F initial closing | Private syndicate including Atreides | Anticipated $3.9B; $30.9B post-money | www.crusoe.ai |
| 2026-09-17 | Form D: options, warrants or other rights | Instrument or proposal; no new ownership allocation established | $595,943,098 sold; 52 investors; Not disclosed | SEC |
| 2026-10-12 | Research check | Private shareholders; complete stakes unavailable | Full anticipated-round closure not established here | www.crusoe.ai |
A $595.9M SEC filing is a different instrument from the round headline
I checked the September 17 Form D: it reports $595,943,098 sold to 52 investors, with the first sale dated July 17. The selected instrument is an option, warrant or other right, with an underlying security. The filing supplies no valuation or investor-by-investor allocation.
That record cannot be relabelled as $595.9 million of ordinary equity cash or substituted for the anticipated $3.9 billion Series F. Nor does it establish an IPO. The meaningful finding is that two contemporaneous financing records describe different instruments and disclosure scopes; adding their headline amounts would risk double counting.
The issuer is Crusoe Inc., formerly Crusoe Energy Holdings Inc., incorporated in Delaware in 2022. That is an entity-incorporation date, distinct from the business’s 2018 founding. The original research here is reconciling these records, not claiming access to a private shareholder register.
Who runs Crusoe?
| Person | Role | As of / condition | Source |
|---|---|---|---|
| Chase Lochmiller | Cofounder and CEO | Confirmed September 2026 | www.crusoe.ai |
Can you buy Crusoe stock? What about an IPO?
No publicly traded Crusoe share or verified IPO date is established by the reviewed records. A financing described elsewhere as pre-IPO does not guarantee when or whether a listing happens. An actual offering needs its own issuer, classes and shareholder disclosure.
The comparison with Lambda’s funding investigation is useful because infrastructure can draw on both debt and equity. Groq’s ownership file adds another distinction: licensing consideration is not a company financing valuation.
Our AI company index places infrastructure businesses alongside model and software companies. The Cohere ownership investigation shows a different reason to question valuation comparisons: a proposed combination changes the corporate perimeter rather than pricing the same standalone company.
Frequently asked questions
Who owns Crusoe?
Crusoe is a private company with founders and institutional and strategic investors. Its latest release names Atreides, Mubadala and Valor as financing co-leads without disclosing their current percentages. The syndicate includes other named holders; it is not a published complete cap table.
Did Crusoe close a $3.9 billion round?
The September company release describes an initial closing of an anticipated $3.9 billion Series F. I retain that wording rather than asserting that the entire anticipated total had already closed. A later final-closing record would be needed to establish the full completed amount.
What is Crusoe’s valuation?
The Series F release states $30.9 billion post-money. The prior Series E release gives an expected value above $10 billion, a lower bound rather than an exact point. Both figures retain their transaction dates and do not constitute current exchange stock prices.
Can you buy Crusoe stock?
No public Crusoe ticker is established in this review. Direct private shares and interests in a vehicle require different documentation. Check the issuer, underlying holdings, fees and transfer conditions rather than assuming that a financing headline makes stock available to every retail investor.
Who is the CEO of Crusoe?
Chase Lochmiller is identified as cofounder and CEO in Crusoe’s financing announcements. The company’s origin account also names cofounder Cully Cavness. Founding status and executive responsibility are separate from present share ownership: the public releases do not provide a complete schedule of founder holdings or voting rights.
What I am watching next
Next closing notice: confirm how much of the anticipated financing actually completes.
Next project disclosure: identify project equity and debt separately from corporate ownership.
Next offering record: verify listing status and capital structure before assigning an IPO timeline.
Our independent research methodology
I read the Series D, E and F releases, company history and origin account. I compared initial-closing qualifications and retained the expected valuation lower bound. Our research approach distinguishes corporate equity from project assets and contracted business. I did not inspect individual project agreements or the shareholder register.
Research checked 2026-10-12. Updated 2026-10-12. Meet the author and read our research approach.
Sources & methodology
Observations retain their source, period and definition. Uncertainty is preserved; missing values are not zero.
- Crusoe closes Series D ↗
www.crusoe.ai · 2024-12-12
Closed $600M at $2.8B; Founders Fund lead. Accessed 2026-10-11.
- Crusoe announces Series E initial closing ↗
www.crusoe.ai · 2025-10-24
Initial closing of anticipated $1.375B, expected valuation above $10B; not an exact $10B observation. Accessed 2026-10-11.
- Crusoe Series F initial closing ↗
www.crusoe.ai · 2026-09-17
Initial closing of anticipated $3.9B at $30.9B post-money, Atreides, Mubadala and Valor co-lead. Accessed 2026-10-11.
- Crusoe company history ↗
www.crusoe.ai · Undated
Founding and transition from energy infrastructure to AI; current site footer uses Crusoe, Inc. Accessed 2026-10-11.
- Crusoe origin: understanding the problem ↗
www.crusoe.ai · 2021
Company account of Chase Lochmiller, Cully Cavness and 2018 beginnings. Accessed 2026-10-11.
- Crusoe Inc. September 2026 Form D ↗
SEC · 2026-09-17
Issuer Crusoe Inc., formerly Crusoe Energy Holdings Inc.; incorporated Delaware 2022. First sale July 17, 2026; $595,943,098 sold to 52 investors. Selected instrument is option, warrant or other right, with underlying security. Not a complete cap table or ordinary equity round valuation. Accessed 2026-10-11.
- Crusoe Cloud legal center ↗
Crusoe · 2026-08-10
Current Cloud terms identify Crusoe Technologies LLC and affiliates as contractual service providers. Contracting entity differs from the SEC issuer. Accessed 2026-10-11.