Key takeaways
- November 2025: over $1.5B of Series E financing led by TWG Global.
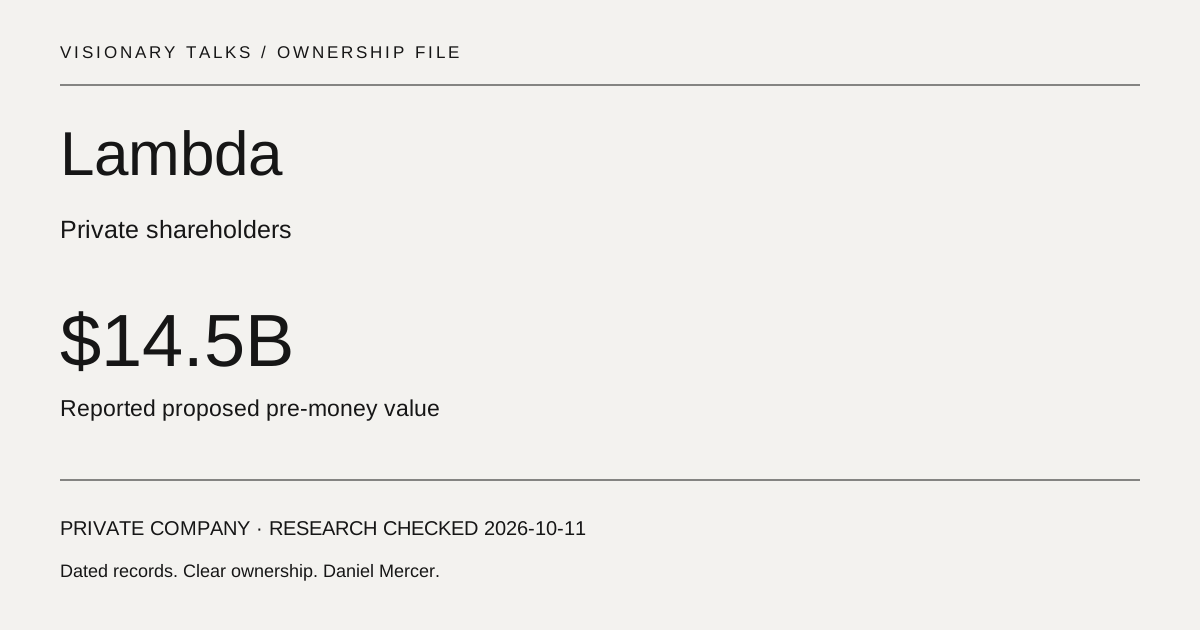
- October 6, 2026 reporting: up to $4B proposed at $14.5B pre-money.
- A hypothetical full raise on those terms would imply $18.5B post-money, before other adjustments.
- August 2026: $926M secured facility priced; that is debt, not a share valuation.
- The August release identifies Michel Combes as CEO; older releases identify Stephen Balaban.
What changed in 2026
Reuters’ account of the WSJ report describes a proposed financing and a conditional 2027 IPO aim. I did not obtain the underlying investor letter. The report does not establish a completed $4B raise or a guaranteed listing.
I checked the May leadership appointment, the August loan closing and the October fixed-rate financing. They update management and completed debt financing without turning either loan into an equity valuation.
Who owns Lambda?
The completed round releases identify institutional backers and strategic participants. The proposed new leads belong in a clearly conditional row. Naming Blackstone and Coatue as owners on the strength of an unclosed financing report would turn a proposal into a fact.
The company’s terms identify Lambda, Inc., a Delaware company. This is the GPU cloud business, not a stock issued by an unrelated product using the same name. A legal entity check helps prevent search-query ambiguity from contaminating ownership research.
| Holder | Type | Stake / basis | Voting rights | Source / date |
|---|---|---|---|---|
| Founders and other private holders | Private shareholders | Not disclosed | Not disclosed | lambda.ai Historical holders; percentages unavailable |
| TWG Global; USIT | Series E lead and participant | Not disclosed | Not disclosed | lambda.ai 2025-11-18 |
| Andra Capital; SGW | Series D co-leads | Not disclosed | Not disclosed | lambda.ai 2025-02-19 |
| Nvidia | Named Series D participant | Not disclosed | Not disclosed | lambda.ai 2025-02-19 |
| Blackstone; Coatue | Reported proposed-round leads | Proposed allocation not disclosed | Not established by report | www.aol.com 2026-10-06; not verified closed |
Who owns the GPUs pledged to Lambda’s loan facility?
The August announcement describes a GPU asset-backed SPV structure with security over infrastructure and contracted cash flows. It does not provide a full corporate equity allocation or demonstrate that lenders became ordinary shareholders.
That difference matters in an infrastructure business. A lender’s security interest and repayment claim operate differently from a shareholder’s residual claim. The issuer, borrower and asset-owning project vehicle may also be separate entities. The public release does not reproduce all executed documents.
A credit rating for a particular facility should not be silently reused as a rating of every Lambda obligation or a claim that equity cannot lose value. I would need the facility’s actual borrower, guarantees, collateral and covenants to describe the entire liability chain.
Debt investors, founders and a possible IPO
The August 27 closing release resolves the question left open by the earlier pricing announcement. The $926M term loan B is closed. It is backed by GPU infrastructure and the associated contractual cash flows. The lenders’ asset security and repayment rights answer a different ownership question from the holders of Lambda’s equity.
The October fixed-rate financing adds another clearly documented transaction: a delayed-draw facility of $1.008B in its highlights, priced at 6.78% with a final maturity in May 2033. It supports three deployments for two investment-grade offtakers. The draw structure means an announced commitment and immediately received cash should not be treated as interchangeable.
The practical implication is that the financing stack cannot be reduced to a single total raised. Equity supplies ownership capital; debt supplies contractual funding with repayment obligations; customer contracts support the cash-flow story. Adding all three categories together would obscure the liabilities and ownership rights a stock investor actually needs to understand.
A facility rating is also narrower than a rating of every obligation of the parent company. Asset collateral, contract terms, maturity and amortization matter to that assessment. I report the facility’s terms with its own date, rather than using the investment-grade label to endorse a future equity offering.
The banks named in these releases arranged debt. Their presence does not verify the separate claim that banks have been hired for an IPO. The reported 2027 listing objective remains a plan, and the reported up-to-$4B equity raise remains proposed. Completed debt closings are important evidence of access to capital, but do not prove that those other transactions have closed.
How the founders built Lambda
The May 2026 leadership announcement confirms that Stephen and Michael Balaban co-founded Lambda in 2012. It places Stephen in the CTO role and Michael in the CPO role, while appointing Michel Combes CEO. The founder story therefore continues inside the business after the operational leadership change.
This is a useful correction to older financing reports calling Stephen CEO. A title was accurate at the date of those announcements; it became outdated after the later appointment. I use the latest dated company record for management and retain older titles only when describing their historical context.
The company’s formation and financing history do not disclose the brothers’ present interests. Founder ownership, accumulated dilution and liquidity need their own evidence before either receives a personal net-worth estimate. The price of the company’s infrastructure or the value of a proposed funding round cannot substitute for that work.
Funding and valuation history
The Series C and Series D posts verify money raised and named participants but omit exact company valuations. I keep those cells undisclosed instead of borrowing unsourced secondary-market estimates.
Pre-money and post-money are not interchangeable. Under the reported maximum scenario, $14.5B plus $4B would imply $18.5B after the financing, assuming the amounts are entirely primary equity and ignoring other capitalization adjustments. This is conditional arithmetic, not a completed transaction price.
Under the same simplified assumptions, new money would represent approximately 21.6% of post-money value. That is not Blackstone’s share or Coatue’s share. A joint lead can subscribe only part of the total, other investors can participate and option-pool changes can alter effective dilution.
The secured facility is excluded from capital-raised-as-equity arithmetic. An asset-backed borrower has repayment obligations even if the wider company is private. Calling a loan an investment does not make the lender a corporate shareholder.
| Date / event | Amount | Valuation | Lead / counterparty | Evidence |
|---|---|---|---|---|
| 2024-02-15 Series C | $320M | Not disclosed in opened company release | USIT | lambda.ai disclosed |
| 2025-02-19 Series D | $480M | Not disclosed in opened company release | Andra Capital; SGW | lambda.ai disclosed |
| 2025-11-18 Series E | Over $1.5B | Not disclosed in opened company release | TWG Global; USIT | lambda.ai disclosed |
| 2026-08-27 Secured term loan B closed | $926M | Debt, not company valuation | Morgan Stanley; MUFG as arrangers | Lambda disclosed |
| 2026-10-01 Fixed-rate delayed-draw term loan closed | $1.008B facility | Debt, not an equity value | J.P. Morgan as debt arranger | Lambda disclosed |
| 2026-10-06 Reported proposed financing | Up to $4B | $14.5B pre-money; not closed | Blackstone; Coatue, reported | www.aol.com reported |
A valuation trend would require at least two comparable priced rounds with exact values. The table preserves the available evidence without manufacturing a chart.
The opened company equity releases omit exact valuation figures, and October’s proposed price is not closed. I therefore do not manufacture a valuation trend. The funding table and dated timeline provide the verified history while keeping missing values visible.
Lambda ownership timeline
| Date | Event | Ownership after event | Money / basis | Source |
|---|---|---|---|---|
| 2012 | Company founded | Private founders and backers | No founding valuation assigned | lambda.ai |
| 2024-02-15 | Series C | Private syndicate including USIT | $320M; valuation not disclosed in release | lambda.ai |
| 2025-02-19 | Series D | Private investors including Nvidia | $480M; valuation not disclosed in release | lambda.ai |
| 2025-11-18 | Series E | TWG Global and participating private holders | > $1.5B; valuation not disclosed in release | lambda.ai |
| 2026-08-12 | Secured facility priced | Lender claims do not establish ordinary equity ownership | $926M; closing expected subject to conditions | lambda.ai |
| 2026-08-27 | Term loan B closes | No new equity interest established by debt closing | $926M secured facility | Lambda |
| 2026-10-01 | Delayed-draw fixed-rate facility closes | Debt instrument; company remains private | $1.008B facility | Lambda |
| 2026-10-06 | Financing plan reported | Proposed new holders, not verified closing | Up to $4B at $14.5B pre-money | www.aol.com |
| 2026-10-12 | Research check | Private shareholders; proposed financing conditional | 2027 IPO aim reported, not confirmed schedule | www.aol.com |
$14.5B pre-money cannot be compared directly with a post-money round
I checked the legal operator and separated its debt financing before doing the conditional arithmetic on the reported round. The result is a proposed maximum post-money scenario, not a new historical valuation bar.
My read: an ownership article should show the assumptions beside the number. The $18.5B scenario depends on the full reported raise completing as primary equity on those terms. A smaller amount or a secondary component would change the calculation.
The debt record adds a second checkable finding: it describes asset-backed financing rather than a purchase of all company shares, and identifies a newer CEO. Large funding totals are not enough to classify ownership or leadership correctly.
Who runs Lambda?
Can you buy Lambda stock? What about an IPO?
The reported IPO aim is conditional on execution and market conditions. It is not an exchange admission or a published offer price. A private financing proposal can change before closing, and a projected listing can be delayed.
A bank arranging secured debt does not automatically have an IPO underwriting mandate. The August release identifies facility arrangers, which I do not repurpose as proof of an IPO bank appointment.
For context, Crusoe’s ownership history highlights initial closing qualifications; Groq’s licence investigation explains consideration without share acquisition. The AI companies index keeps financial observations tied to their definitions.
The Mistral AI ownership investigation separates a strategic investor from a corporate parent. The Glean investigation follows company equity funding. Both comparisons help explain why a bank arranging a loan is not automatically an equity owner of Lambda.
Frequently asked questions
Who owns Lambda?
Lambda is private, with founders and institutional and strategic investors named in its closed rounds. TWG Global led the last opened Series E release. Blackstone and Coatue are reported prospective leads in a proposed financing, not verified current owners through a completed round.
When is Lambda’s IPO?
Reuters reported a conditional 2027 aim based on WSJ reporting. I have not obtained a public offering document establishing a schedule. A target year depends on execution and markets and should not be written as a guaranteed date or already available public stock.
What is Lambda’s valuation?
The October financing proposal was reported at $14.5 billion pre-money. A full $4 billion primary raise would conditionally imply $18.5 billion post-money before other adjustments. Neither number is a verified closing price in this investigation, and neither belongs on a completed-round chart.
Is Lambda owned by Nvidia?
Nvidia was named as a participant in Lambda’s Series D. That establishes an investment relationship at that date, not majority ownership or a corporate parent. A complete contemporary stake and voting percentage are not supplied by the opened financing releases.
Is Lambda owned by Amazon?
Lambda, Inc. is the independent AI infrastructure company discussed here. Amazon’s AWS Lambda is a different cloud service, despite the shared word in their names. Lambda’s company financing records identify its own founders and investors; a similar product name does not establish that Amazon owns this business.
What I am watching next
Next company notice: verify whether the October financing closes, its actual size and pre/post-money basis.
2027 aim: look for offering records and an actual public schedule before updating listing status.
Debt refresh: check closing confirmation and borrower terms rather than treating an expected facility close as completed.
Our independent research methodology
I read company equity releases, the secured-facility announcement, legal terms and Reuters’ report. The underlying WSJ letter was not obtained independently. Our research method keeps reported proposals separate from primary disclosures and clearly labels hypothetical calculations. I did not obtain private share or loan agreements.
Research checked 2026-10-12. Updated 2026-10-12. Meet the author and read our research approach.
Sources & methodology
Observations retain their source, period and definition. Uncertainty is preserved; missing values are not zero.
- Lambda Series C ↗
lambda.ai · 2024-02-15
$320M USIT-led round, investor identities; announcement does not disclose valuation. Accessed 2026-10-11.
- Lambda Series D ↗
lambda.ai · 2025-02-19
$480M led by Andra Capital and SGW; Nvidia participating; valuation not in release. Accessed 2026-10-11.
- Lambda Series E ↗
lambda.ai · 2025-11-18
Over $1.5B led by TWG Global with USIT; founded 2012 and Stephen Balaban cofounder/CEO. Accessed 2026-10-11.
- Reuters reporting of WSJ Lambda financing plan ↗
www.aol.com · 2026-10-06
Up to $4B at $14.5B pre-money, Blackstone/Coatue; conditional 2027 IPO aim. Underlying letter not independently obtained. Accessed 2026-10-11.
- Lambda website and hardware terms ↗
lambda.ai · 2025-08
Identifies Lambda, Inc., a Delaware company; does not establish share ownership. Accessed 2026-10-11.
- Lambda secured term loan B pricing ↗
lambda.ai · 2026-08-12
GPU asset-backed SPV facility priced at $926M; expected close subject to conditions; identifies Michel Combes as CEO. Accessed 2026-10-11.
- Lambda appoints CEO, CTO, CPO and chairman ↗
Lambda · 2026-05-05
Updated May27. Michel Combes CEO effective May2026; Stephen Balaban CTO; Michael Balaban CPO; John Donovan chairman. Both Balabans founded Lambda in 2012. Accessed 2026-10-11.
- Lambda closes $926M term loan B ↗
Lambda · 2026-08-27
Confirms closing after August12 pricing. GPU asset-backed facility, contractual cash flows, Moody’s Baa2 facility rating; Morgan Stanley and MUFG arrangers. Accessed 2026-10-11.
- Lambda closes fixed-rate GPU financing ↗
Lambda · 2026-10-01
Closing of approximately $1B delayed-draw term loan; facility highlights $1.008B, 6.78%, final maturity May30 2033, three deployments/two offtakers. J.P.Morgan is debt arranger, not proof of an IPO mandate. Accessed 2026-10-11.